

Who is Adam Stosio?
- Who he is
- Adam Stosio, who has worked on currency risk management for 28 years. For 20 years he worked in corporate banking, and for the last eight he has been a practitioner and fan of fintech solutions, at one of the dynamically developing fintech firms in Europe (Ebury).
- What he does
- He helps small and medium firms, including software houses, implement currency risk management rules. He initiated a survey of finance management in the Polish IT sector, carried out together with the SODA Association. He works with almost sixty Polish software houses.
- What we talk about
- What currency risk is, groups of currencies and the position of the dollar, risk management rules, the hedging plan and forward transactions, the costs of hedging, the results of a survey of Polish IT firms, strategic and operational goals of hedging, the specifics of SaaS and B2C, and the most common mistakes.
- Where to find him
- LinkedIn (Adam Stosio).
Best quotes
„Managing is not hedging.”
„Not hedging is speculation.”
„Currency risk is our daily bread.”
„Everything has already happened.”
Recommended materials and sources
Guest’s pick
 lubimyczytac.pl


Related conversations


Transcript
Host: Rafał Moszkowców. Guest: Adam Stosio.
Introduction
Rafał: Hi everyone! Welcome warmly to another episode of the Globalne Horyzonty podcast. Today I have the great pleasure of hosting an exceptional person from the Polish world of finance, Adam Stosio, who combines 20 years of experience in corporate banking with work at one of the most dynamically developing fintech firms in Europe. But I think Adam will introduce himself and say more about what he does. Hi Adam, welcome.
Adam: Hi, hi Rafał, welcome to all the guests of our podcast today. This is my first occasion to appear on Rafał's show. I hope not the last. So forgive a bit of stage fright, if it should happen. Rafał has already introduced me in part, but indeed for 28 years I have dealt with currency risk management, which will be the main topic of our meeting today. Of that, 20 years in corporate banking, and for 8 years I have been a practitioner and fan of fintech solutions, also in this area, which I hope I will have a chance to share with you.
What is currency risk?
Rafał: I think we will definitely talk a lot about this, because a lot is happening on the currency market. Many topics in expansion rest on financial risk, currency risk, so I very much wanted to talk with you, because I know the firm you work for every day, Ebury, specializes in hedging those risks, so I think it will be a very valuable conversation. Let us get straight to the point. What is currency risk really?
Adam: We start with the definition and textbook, but also very precisely. Currency risk is the risk of incurring a loss or not realizing a planned profit on commercial and financial transactions as a result of a change in the exchange rate during the settlement of that transaction in the different currencies in which we settle.
Rafał: So if we were to simplify, it is one of the elements of the risk that if you do not take care of it at the start, third forces can change the amount of funds you actually earn.
Adam: Yes. If we were to simplify, let us listen to examples. For ease I will use the example of a Polish exporter today. I will tell you later why, mainly because it is mainly exporters who hedge currency risk. Of course the same applies to the importer's side. Let us imagine you sign a contract, a situation taken from life. I will try to refer to the point where we are now, as well as to what happened a few months ago. At the end of the year you conclude a commercial contract in which you will receive a million dollars from a client. Now you would have to somehow plan your budget. At that time the dollar rate at the end of the year was 4.10 to the zloty. And the question arises of what to do about that currency risk. If you did not hedge it, then at the moment we are dealing with a dollar rate of 3.75. The transaction is settled, because payments were set for the current period. As is easy to calculate, the loss reaches 7-8 percent, a loss or an unrealized profit. That is the practical dimension of currency risk, which we face daily, which I face working with many Polish entrepreneurs. In particular I wanted to draw attention to a fact that I think we all deal with: the times of calm on financial markets are already over, if they ever existed at all. Now it is much less pleasant in this respect. The balance of risks has gone up in every respect and we should expect that it will stay that way.
What are the three currency groups and where does the dollar stand?
Rafał: And does it concern every currency? Or are there currencies that are the most risky in the sense that their valuation against the zloty changes most often?
Adam: The world of currencies should be viewed by grouping them into three groups. The first are safe haven currencies. A fundamental change has taken place here, by the way, which I will tell you about in a moment. Safe haven currencies are currencies that strengthen, meaning their rate rises against other currencies, whenever some risks rise in the world. A conflict breaks out, a pandemic appears, very bad economic data comes out. What do we do then? We sell risky assets, meaning the currencies of riskier countries, and we buy safe haven currencies. Which currencies are those? Until now, first of all the dollar, the Swiss franc, the Japanese yen. As for other asset classes, of course gold, silver and metals of that kind. Next we have the major currencies, meaning the currencies of developed countries, generally the so-called G10. Besides the three I mentioned, there are currencies like the Australian, Canadian and New Zealand dollars, the Swedish and Norwegian krona, that more or less closes that area, and all the rest of the currencies belong to the group of currencies of developing, riskier countries. Of course here too there are more and less risky currencies. Nevertheless the principle is fundamental. If something bad happens in the world, if the so-called risk aversion of investors, caused by the appearance of some global risk for economic growth, for the possibility of earning money safely, increases, we sell risky assets, which in favorable times may bring high returns, but in unfavorable times lose very strongly against major currencies or safe haven currencies, and we buy those from the first two groups. Here one extremely important remark. This year we are of course dealing with the Trump effect and all the derivative effects that follow. In the area we are discussing, what has been undermined so far, only undermined, is the position of the dollar as a safe haven currency. Normally, if decisions such as introducing tariffs by the Trump administration, resulting in a potential collapse in foreign trade and a reduction in economic activity in the world, appeared on the horizon and began to be put into practice, the dollar should strengthen, because that is historically the normal behavior of investors, meaning all holders of any assets represented by financial institutions, banks, funds. The normal behavior is: I sell risky assets, I buy the dollar. Meanwhile the dollar weakens. Why? Because besides the purely economic effects of Trump's decisions, issues arose about the predictability of those decisions. We all see and observe: once a tariff is introduced, once switched on, once switched off, this country yes, that country no. Investors lost trust in the economic decisions of the Trump administration, and another element is the attempts, expressed several times, to undermine the independence of the central bank, meaning the Federal Reserve of the United States, by the president and the administration. That again lowered trust in the dollar. The dollar still remains the main currency in international economic trade. At the moment its share is still dominant, around seventy percent of all trade transactions are denominated in dollars. Nevertheless those factors are starting to be visible. Returning, and sorry for this overlong exposition, I keep going without a break.
Rafał: Not at all, it is very interesting.
Adam: I try to close it with a bracket, remembering your question whether there are currency pairs that are less or more volatile and risky. We can say that there are in fact no less or more risky ones from the point of view of exchange rate volatility. Signing a contract now in euro, for example as an exporter, I can count, but only count, that the euro rate to the zloty is somewhat more stable than the dollar to the zloty for the reasons I just mentioned. But that does not change the fact that soon the situation may reverse and the euro to zloty rate may also become much, much less stable than we observed last year or still observe this year.
Rafał: Thanks for that explanation. There are theories that the dollar is being weakened deliberately to increase the export possibilities of the United States. I do not know if it is a conspiracy theory, because I read it in a serious economic journal. It is a side note, because I listen and read a lot on this subject and do not quite understand it, because it seems to me that the whole debt of the American administration rests on the dollar being in circulation. If the dollar drops out of circulation even by a dozen or so percent, that debt will stop being rolled over and it could be a great tragedy, because the valuation of American bonds already does not look as nice as it should according to the budget plan. So these are odd moves and interesting that from the perspective even of a Polish exporter, I am not saying a small export, because later it may be a huge firm, you have to pay attention to what is happening in Washington, what is happening in Beijing, and try to defend yourself. That brings me to a question to which, if anyone knows the answer, you surely do. How can you deal with these currency risks, taking it seriously?
How can a company cope with currency risk?
Adam: As you said, the currency market is the largest financial market in the world. Let us remember that 9 out of 10 units of currency, euro or dollar, traded on the currency market have no backing in the mass of goods and services. It is simply speculative, investor money. That fact, combined with the number of factors from macroeconomic data, from central bank statements, from geopolitical factors like wars, pandemics, from the most varied statements of decision makers, is so enormous and so unpredictable that trying to predict trends on the currency market is a game doomed to failure, and certainly not for a trading, industrial firm, an SME sector firm, or even a corporation. So the only answer is implementing currency risk management rules in firms. And here I will say right away, returning to my history: during those 20 years in banking I worked on and took part in the processes of implementing risk management policies in large Polish and international corporations. For the last eight years in fintech I have been carrying the torch of enlightenment precisely in the sector of small and medium enterprises, although I actually call them, it is an English-language phrase that appeared on the market, small and medium multinationals. If we look at the revenue of such a firm, it falls somewhere into the category of small and medium enterprises. If we look at how it operates, selling to ten foreign countries or more, it has exactly the profile of an international corporation present all over the world, with all the problems, with all the volatility of exchange rates. I had to reprogram my approach to this problem a bit, so as not to scare a partner with the word "policy". Policy is associated with how it really looks: sometimes dozens, hundreds of pages of procedures introduced in a large corporation, which are to say who, where and how is to deal with elements of currency risk management. It turns out that reducing those rules literally to a few basic steps was not hard at all, and if you want I can tell you about them. And that is exactly the answer to the question: introduce procedures, processes, rules of understanding and managing currency risk.
Rafał: I would very much like you to say that, because I think from the perspective even of a medium exporter, but also an importer, it is important. If you can, explain it further.
How do you identify a company's currency position?
Adam: Good, let us reduce it to the absolute essence. First, managing is not hedging. There are firms that do not hedge currency risk, consciously leave it open, but they manage it. That is the first point in our ABC, which could be composed of five to eight such rules, processes. The first is identifying and analyzing currency risk. What does that mean? We must ask the whole firm where currency risk arises in the firm. Of course it is the sales departments, so for example export in the case of an exporter. It is the purchasing departments in the case of an importer, import from abroad: they decide how much they buy, how much goods or services, in which currency they pay for it, when they pay. That is where currency risk arises. But not only. Currency risk is also taking out a loan, the area of the finance director, who can take a loan in a different currency at a bank, and that again affects the so-called currency position of the firm. What is a currency position? The currency position, in the case of an exporter, simplifying, is the surplus of revenue in a given currency over its costs. Let us imagine an extreme example of a firm that has 100 percent of revenue in euro and 100 percent of costs in zloty, and that revenue in euro is 10 million euro a year. The firm's currency position is 10 million euro a year. It is called an exporter's position. In slang it is the so-called long position, versus the importer, the so-called short. That is the first thing: identifying the currency position. We must know what risk we are sitting on. Trying to introduce these rules in a firm, you should add and describe which positions are responsible for it. We already know who creates this phenomenon, who should raise a hand and say: yes, I signed export contracts for this many million euro and import ones for this many million dollars. Then we create from this trivially simple management information. In my example I already showed how it should be done.
What is a hedging plan and what should it contain?
Adam: Knowing that, we move to point two: preparing a hedging plan, which should include the following elements. First we must answer the question of what part of our currency exposure we want to hedge. That is, for what percentage of our currency exposure we want to get rid of the problem of exchange rate volatility, enter a hedging transaction that will guarantee us a fixed exchange rate of one currency to another in the future, in our example euro to zloty. What percentage should that be? Never a hundred. Because we rely on sales plans. They may not come to pass, they may shift. A good practice is hedging a maximum of 75 percent of the plan, a minimum of 50. A minimum of 50 because those hedges should be effective. If we eliminate currency risk, meaning the risk of incurring a loss on our export contracts, for 50 percent of our foreign revenue, then even if the other half stays open and something unfavorable from the exporter's point of view happens, meaning the rate falls, the firm will still survive. It will earn less, but we will not wipe out the firm entirely on those plans, on those contracts. Another thing is a common sense approach: the hedge coefficient I mentioned, 50-70 percent, is called the hedge ratio. It can often be, and even should be, higher for nearer periods. What I see in the nearest quarter, what I am sure I invoiced, that the client will pay me in euro, I can hedge a bit more. In the following quarters we hedge a bit less, and later we top up the hedging of that currency risk to appropriate levels. A very nice tool is examining the sensitivity of our financial result, at the EBIT level, gross or net, as anyone wishes, to a change in the exchange rate. Let us ask ourselves not only by how much our revenue changes with a ten percent strengthening of the zloty against the euro, because obviously by 10 percent, but what impact it will have on our financial result in general. If we have big margins, the result will be somewhere there, but it will not be so painful. If those margins are thin, we can go in with an installment and wipe out the firm. All of this should be in a hedging plan written on a slip of paper. For those interested, I hope Rafał will share my contact, I will show you how literally on one A4 sheet such a hedging plan should look, but it should contain elements like the firm's currency position spread over time, for example the next 4-5 quarters, the hedge ratio in the individual quarters I mentioned, and we go on: the exchange rate, at what level of rate we want to hedge. Such a rate is usually, as a minimum, the so-called budget rate. Every firm, thinking either about a single foreign contract where it will achieve revenue in a currency, or, if it runs continuous activity, about a budget plan for the next settlement periods, a financial year, wonders at what rate to convert its costs in zloty, add a margin so that it yields an amount in euro that is to be our price offer to the client. This budget rate is usually, and good practice is to set it below the currently available spot rate, meaning the current one. Why? Because even if we have transaction hedging plans and want to implement, or have already implemented, these rules in the firm, we have the instruments ready, we make a financial plan in November, for example, and calculate it at the spot rate of 4.30, subtract 10 groszy, let it be 4.20, or even 20 groszy, so that when in a month or two all our planning is confirmed and we really carry out currency transactions, we can still catch that budget rate, even despite a short-term strengthening of the zloty against the euro, meaning a fall in the rate. The point is to approach it a bit conservatively. Everything I say, flip it over to the importer's side: there the budget rate should be set slightly higher, above the available spot rate. That is almost the last element of the whole puzzle in the hedging plan. Of course the hedging plan must then also record which transactions we use. In the small and medium enterprise sector we recommend forward currency transactions, possibly a mutation of the forward with a settlement window, which lets you guarantee a fixed settlement rate not for one date in the future, but for a period from to, which lets you avoid the perturbations typical of the SME sector resulting for example from delays in receivables.
How much does hedging currency risk cost?
Rafał: I was just going to ask about that, because I think it is really important and accessible. Before we go on, you said so much on this subject and it seems on one hand obvious, on the other complicated. Many listeners may ask themselves whether it is for me, whether I can even afford it. What costs may be connected with it? Is it settled in percentage terms of our risk, of the currency we hedge? Can you expand a bit?
Adam: First, forward transactions as such carry no fees. You will probably ask where the profit of the financial institution, a bank or payment institution, is. We live on margin. If I agree that I will buy from my client and guarantee them a purchase of euro next year at a rate of 4.25 for the whole year, I replicate a similar transaction with a bank and give it that currency at a rate of 4.27. Those 2 groszy are my profit and my remuneration for knowledge, for providing the tool called a forward transaction, for maintaining an office, and also for the credit risk connected with that transaction, because there is an element of credit risk there: if the firm with which I conclude the transaction did not settle it for some reason, for example did not achieve those euro revenues, I have to settle that transaction with my partner to whom I gave that currency in a back to back transaction. I have to buy that currency at a rate I do not know in the future. It may simply be higher and that difference then constitutes a component of credit risk. It is all written into the profit margin that we or banks want for it. Remember also that it is not pure profit for the financial institution, there are costs to cover. There are of course transactions that are paid, the so-called currency options. It is a kind of insurance, in the case of an exporter, against the rate falling below some level: the financial institution guarantees that in the future it will buy back from the client, for example, euro at a rate of 4.25 and never lower, but at the same time if the rate is higher, the client can benefit from the higher rate. Like any insurance, it is, unlike a forward, a paid transaction and some percentage of the nominal of that transaction has to be paid straight away. But as I say, in the case of the SME sector the most popular tool, the simplest and most understandable and clear, remains the forward.
What does the SODA survey say about currency risk in Polish IT?
Rafał: Of course I will link your contact at the very end, so anyone who wants to find out more can talk to you. From my experience a great many firms, especially from the SME sector, I look at it somewhere between 2 and 10 million euro, do not professionally hedge their currency risk at all. That may be only my bubble, because I have not carried out larger studies, but we will talk about studies in a moment, because I know you did something in this area. I have many times seen very big problems with it: that money was not hedged and the margin escaped. My honest question: you have worked for many years in Poland with Polish firms, you specialize in working with firms from the broadly understood IT sector, so I am honestly curious how Polish firms cope with it and whether they cope. I expect honest answers.
Adam: Sure, I will say it from the general to the specific. Generally it is good. The Polish exporter, the Polish importer is a success story. 25 years ago we were a not very open economy, where the share of foreign trade in GDP probably did not exceed twenty percent. At the moment it is clearly above fifty percent. We are really masters of foreign trade. I say that very boldly and not only because we sell a lot or buy a lot to later sell even more abroad, but because we have built a very diversified export-import sector. We are not dependent, like the Czechs or Hungarians, only on the automotive sector, which is always risky. A Polish element of that success was also education and learning, in which I myself, learning and teaching, took part over all those years, in the area of currency risk management. If we look at standard industries, including the high-margin industries we associate with the software, IT and high-tech area, then implementing those solutions, acquiring knowledge and applying it effectively and, most importantly, consistently, according to adopted rules implemented in the firm, is extremely important, so as not to approach hedging ad hoc, because that will not work. Solutions of that kind were also an element of that success. The Polish entrepreneur learned it and applies it, because otherwise he would simply not exist. The volatility of exchange rates averages 6.3 percent a year for euro to zloty and over 11 percent for dollar to zloty. That is by how much the rate on these two pairs can deviate from the average, based on historical data. Such moves can easily eat any standard margin. Standard trade margins are a few percent, production maybe a bit more, but lack of hedging could end badly. Generally it is not bad. Moving to our beloved industry of IT, of broadly understood new technologies, in which both you and I make our living, here it is much worse, and let me use hard data. I can talk about it so easily because I was the initiator of the first research project on managing financial areas in the Polish IT sector. We did it together and with the great participation and help of the SODA Association. This report was created at the turn of last year and this year, and was published in March. I encourage you to read it, it is available on SODA's website and also on Ebury's website. I hope Rafał links it somewhere.
Rafał: Do not worry, I will definitely link it, because I think it is very valuable.
Adam: A small remark: the report concerns in fact seven, eight main areas of the finance director's responsibility, not only payments or currency risk, which I deal with, but also taxes, investments, financing, M&A and so on. Returning to my part, the survey is very statistically significant, because we received 100 questionnaires from the largest to the smallest companies, and the questionnaire itself was 60 questions, so it was not small, thanks to all the firms and partners for devoting their time. It turned out that only 34 percent of Polish IT firms actively manage, meaning hedge, currency risk, but it looks even worse, because only 18 percent of them do it on the basis of adopted, fixed, implemented rules. Here, unfortunately, there is a problem, because if it is not done according to adopted rules, in a fixed, consistent and thought-through way, it often ends with a one-off transaction that nobody quite knows why it was made, nobody knows what its goals were. There is a glimmer of light in the tunnel: 26 percent of firms declared that they plan to introduce such procedures this year, and it is really happening. I currently work with almost sixty Polish software houses and many of them are adopting such consistent rules.
Why should a company manage currency risk?
Adam: Let us return to the goals: what are this policy, these rules, this currency risk management actually for. There can be many goals, but two current, operational ones are, first, protecting the trade margin. If we convert our costs at the budget rate and build our margin into it, we want to achieve that margin, so that a change in the rate in a direction negative for us simply does not consume that margin. The second thing is flattening currency flows, meaning cash flow in the currency in which we incur costs. The point is that we know the proverbial million euro received every month will be 4.25 million zloty every month, and not every month 200 thousand more or less, because such volatility, meaning a situation without hedging the exchange rate, makes it very hard to plan the future in many areas. First, to invest: if we do not know what margin we will have from month to month, how do we take out a loan and finance it from our margin, which we do not know will exist. How do we remunerate people, who are paid in zloty, from their remuneration, from their sales goals, not knowing whether we will get 200-300 thousand zloty less or more from a realized contract. Those are the two basic goals. I wanted to draw attention to even more strategic goals, especially for those of you who think about preparing the firm for the public market or for letting in an investor, or selling the firm at all: in the long term procedures of this kind raise the value of the firm, because in every firm valuation model there is an element of volatility. If a firm earns great in one quarter and worse in the next, and volatility occurs, which you see through financial statements expressed in zloty, and that firm is susceptible to volatility resulting from exchange rate changes and does not hedge, it distorts the picture of its finances and operations. We do not know whether it earns well or badly, why that volatility exists, whether it is seasonality, whether it will always be like that, whether soon there will not be even worse results. If we effectively implement such a policy, that volatility disappears or is greatly flattened, and then an investor, an analyst at a fund or an analyst of an industry firm wanting to buy your enterprise will be able to value the firm higher. Solutions of this kind build the value of the enterprise, like all other procedures introduced in a firm.
Rafał: Stability is always rewarded, stability in the revenue area and procedural hedging of it. Anyone who wanted to buy any firm would pay attention to whether the firm has big revenue fluctuations or not, the same with costs, because it determines the financial projection. I know it is often neglected, because I neglected it very often myself. In the heat of battle you can not look at such things if you do not yet have the right people in the right positions who bring that knowledge to the organization. Great that we talk, because the firms I work with very often do not yet have the right people in the right places.
From what exposure level should a firm manage currency risk?
Adam: I wanted to jump in, sorry, but let it resonate on this forum. You raised this several times and that is no surprise, because we work in a similar segment of SME firms. I in the broadly understood, from I do not know ten million zloty of revenue to a billion zloty of revenue, but the bulk are those smaller firms, and here I would like to encourage everyone who runs these smaller businesses to look at this at an early stage of your foreign expansion. First, not to be afraid, because these rules can be simplified a bit and introduced in a simplified version in a smaller firm, where we do not have all the functions of finance director, controller, or the person responsible for reporting, as is the case in larger firms, but already acquire knowledge, an understanding of currency risk and dealing with it. I am well aware that an IT firm in particular has to grow into certain things, because simply, as you said, there are no people for it. But this problem and these people should appear at least in some part from the level of currency exposure of roughly 1.5-2 million euro or dollars of export or import. The presumption is that then the firm can afford or should invest in such functions, or add this element to the area of the finance director, who should already exist in the firm. Below that level I gladly often share knowledge with smaller firms, but I tell them: for now focus on building the basic value of the firm, developing your business, because it is a bit too early. I can do it for you, but it requires some work, there are some costs, at least of time, which for now you should devote to developing foreign sales. And once that works, we go with the topic.
Why does the IT industry neglect currency risk?
Rafał: Great. I would like to go back for a second to a question I wrote down. We talked about our industry, meaning broadly understood IT, and about the survey you did with SODA, which unambiguously says it is not best here. Is it a matter of awareness, or was there another reason? I guess what the reason may be, but I will let you answer. Why in an industry in which in Poland, I do not know the full data, but I think we can say that 90 percent plus of the revenue of software, IT, AI, development, SaaS firms comes from abroad, was there not that awareness? As you were telling it, in my head was: God, I thought this area would be the best looked after, because the exposure to currency risk in those firms is sometimes 90 percent of revenue or 100. What happened here?
Adam: I think the fundamental reason for the state of affairs three years ago was a certain comfort in which our Polish export industry, super successful IT, technology, remained, meaning high margins. Margins reached sometimes 30 percent net. Then, if our revenue decreased by 5 percent, because the euro weakened against the zloty, meaning the rate fell by 5 percent, it was not a big problem. Often it was not even noticed. In my view that is the fundamental problem. Those times ended for various reasons: the cost of financing capital went up, the number of contracts decreased, contracting processes lengthened, it is harder to win a client, engineer costs still remain high despite the changes that AI and copilots of course introduced. On top of that came ever greater currency volatility, including the strengthening of the zloty since 2022, meaning since the end of the pandemic era, when the zloty remained artificially weakened. The second reason, and this will not be criticism of our IT entrepreneurs.
Rafał: It is a footballist.
Adam: Well yes, maybe, but it is also the work environment in such a firm, where really every position has plenty to do. They work terribly hard there. I experience this with managers, owners, founders of IT firms, where everyone says: great, that is a topic, we put it in the book of work for October next year, and we call, and they call in October next year, but not earlier, because they simply have a great deal on their heads and an hour of work is priced very high, so they also have to make a gradation of those problems, and that currency risk problem moves gradually higher and higher. Hence we have more and more conversations in this area.
Rafał: Is it changing a lot? I mean, is that awareness already broad and common?
Adam: It is changing a lot. Awareness is already clear and large. Acceptance to take action is not yet the greatest. Of course there are differences between large and small firms, but that can be deceptive. I know large companies that do not manage currency risk at all. Large, I mean firms with revenue of 100, 200, 300 million. I myself took part a year and a half ago in the process of introducing a risk management policy in one of the largest Polish IT companies, where revenue reached half a billion zloty, and only then was the topic addressed. I would say, a wonder that so late, but once it was addressed, it was boldly and effectively. It is an irreversible trend. Working with IT firms I often present the process, knowledge, tools and possibilities and try not to push specially. If someone says it is not the moment, I know we will meet anyway at the latest in half a year or a year, because those firms can grow effectively only abroad. Of course there is also a domestic segment, but that is a completely different story.
Can currency risk be hedged in SaaS and B2C?
Rafał: I have another question that bothers me. We are talking about exporters, and the image in our listeners' ears is probably that these are firms that sign a few, a dozen contracts, each large, easy to price, hedge, predict. I am simplifying. And what in a situation where we have an exporter who exports bits, and it can be for example SaaS, because I know such firms that have 11, 12, 15 thousand clients paying only and exclusively in dollars, and they are from Poland, and in Poland they have seven clients, so that exposure is at the level of a million, a million and a half euro a month. Is that something they can take care of with you? Are you able to serve this kind of situation?
Adam: Absolutely. Currency risk is currency risk and the first example does not differ from the second at all. What is more, the second is a much easier situation to hedge from the point of view of the predictability of currency flows, because if you have three clients and with each of them you have a million euro of revenue, and let us say one of them leaves, the cooperation ends, and you planned the currency exposure according to the best business assumptions at 3 million euro, you hedged 70 percent, meaning 2.1 million, and one client disappears, you are left with two million, and you hedged currency transactions for 2.1. That is a situation in which one should handle the hedge ratio somewhat carefully. It should not be 80 or 75 percent, but closer to fifty. In the situation you mentioned, meaning B2C, all more fragmented payments, from subscriptions, from monthly fees from a large mass of retail clients, a few or a dozen thousand clients, it is never the case that suddenly 30 percent of the market disappears. It is a gradual process. So you can assume greater predictability of those future flows, meaning currency revenue, and adjust a higher hedge ratio accordingly.
Rafał: Nice that you said that, because it seems to me that in such firms the awareness is even lower. If you have an e-commerce that sells sometimes for very nice money and the revenue is there, there is a feeling that hedging currency risk is a bit of speculation, some scheming.
Is hedging currency risk speculation?
Adam: My favorite comment, sorry, I have to step into the logic of what we are discussing. It is my favorite argument when someone says: I do not hedge, because I will not speculate.
Rafał: I have also heard that in my life, though I do not deal with it.
Adam: Well, not hedging is speculation. Let us think about what speculation is. It is submitting to the risk of not knowing the future exchange rate at which we will convert our future revenue in the case of an exporter, or costs in the case of an importer. Hedging closes that risk for us, so it is the opposite of speculation. That is that comment. As for e-commerce, at Ebury we are probably the largest operator of cross-border e-commerce in Poland. We also deal with constructing the payment architecture in which we settle revenue, whether from online shops or platforms, and of course the principle I mentioned holds. It is a fact that our market of e-commerce firms does not yet have too many large entities, so again you have to return to basics and ask whether I am ready, whether my sensitivity to exchange rate changes is significant, is big, whether I should be dealing with it at this moment. The rule of a million dollars of net exposure, if I may advise, should be a red flag that should light up somewhere.
Rafał: In the situation we have on the market, not only in Poland but globally, where margins seem rather to be falling, any hedging of that margin is mega valuable, because I start from the assumption that you control what you can control, and the rest will fall on you anyway.
Adam: Exactly. We hedge many risks and for some reason this currency risk seems so hard, so somewhat intangible.
Rafał: You have to know it.
Adam: We hedge the firm's assets, we hedge against theft of intellectual value, against non-performance of a contract, and we include such hedges across the whole spectrum of our activity as entrepreneurs, what is more we pay for it, because nothing is free, and here it moves into the background. But as I say, I am moderate, as Alan Greenspan, the former head of the Federal Reserve, who was famous for such Aesopian answers, said. When asked what he thought about life after death, he said that as for life after death, he remains a moderate optimist, though he is aware of the existing threats. As if they were asking him about inflation. I will say something similar regarding the projection of these currency risk management rules onto our entrepreneurs of the sector of small and medium multinationals.
Rafał: I once read Greenspan's biography. There were fantastic conclusions and stories in it, how he, flying in a plane, found out about the collapse of the real estate market in the United States at the end of 2007. An incredible description of all that.
Adam: Regarding his language: in one sentence he could say something that the markets took: aha, there will probably be hikes, a hundred percent, no, in fact there will not, and within three sentences those changes took place. He was a testing ground for the first algorithms catching sets of words that created suggestions for the currency market: buy the dollar or do not buy the dollar, sell the dollar. It was the first testing ground, the early 2000s.
Rafał: Interesting, I had no idea about it. Now there is AI, raised on it too, and it probably analyzes a billion signals at this moment.
What mistakes do Polish entrepreneurs make with currency risk?
Rafał: At the very end I wanted to ask you, because we said a lot about the process, about importance, about how to start, and it seems much easier to me now than at the beginning of the conversation. I have the feeling it is within reach, that it is not some financial Himalayas. If my business develops, it is worth getting interested. But I would like to talk a bit more about mistakes, based on your experience, before one enters the process. That is a strategic plan, tactical action not for a month, two, but rather for 8, 12, thinking about net exposure, about the impact on EBIT and so on. What are the main mistakes in Polish entrepreneurs' approach to the problem of currency risk? So we can organize it in one answer and those who have to deal with it know which mistakes to avoid.
Adam: Sure, very practically. That list could be developed for a very long time, but I will give a few statements, thoughts that I often meet and that are exactly those mistakes. Do not take it personally if you made them, you can always call a friend, an FX risk manager, and we will fix the matter. The first is retroactive management of currency risk: I sign a contract for a sale abroad for a million dollars in December 2024. The rate is 4.10. I think: good, in half a year I will get 4.1 million zloty, I will realize a nice margin. It is okay, I won the contract. 3 months pass, the rate is 3.70. Damn: the whole profit, margin, and maybe I even go into a loss. Then we go to the bank, to Ebury and ask what can be done. Well, then not much. With smaller changes you can still do a bit, with big ones not any more. We have to glue those two elements: if we open currency risk, let us immediately look for a solution to limit that currency risk, at least in a significant part. Let us not wait. Related to that is a second element, where I often hear: okay, let us wait for a better rate, because it will surely be better. It will be better sometime, but in the meantime it may also be worse, and in fact nobody knows. Do you want to live, entrepreneur, in a world of the unknown, why, when you can close that unknown at least in a significant part, equal to the hedge ratio. And why do we wait for a better rate? Because we use opinions. Basing a business on opinion, the dollar will surely be more expensive, said my neighbor, who thought it would surely be more expensive because he imports cars from the United States, is a road to nowhere. Very often we form, on the basis of conversations, various opinions, knowledge or conviction about a market which, as we said at the start of our conversation, is absolutely unpredictable and subject to many factors that cannot be controlled. An important element is also what has already resonated: the impact of sensitivity of the firm's actual result. After all we do not run a firm to have big revenue, but to have profit after covering costs and earn good money. If the change in the exchange rate affects our potential future profit sharply, let us react all the more strongly, because you can really do a lot of work, sign a lot of contracts and have little of it, and even wipe out the firm. And once again I encourage you to put these processes in order. Whether you work in, or manage, a small, medium or large firm, it can be done really effectively, efficiently and relatively simply, for firms that do not have appropriate resources in the function of finance director, financial controller and so on. I also have formats of policies, procedures for currency risk management for smaller, medium, large firms, it is the result of my many years of work, and always in the first point of such rules is the rule that we inform the whole firm. We include not only the people from finance, from export or import, but the whole firm, and spread the knowledge that we live on currency risk, that this firm is based on international trade and our result depends on how well we all communicate in this regard. The firm should announce to everyone, not only those fulfilling the relevant functions in this process, but also all the rest, that currency risk is our daily bread and that we will all cope with it together.
Rafał: Thanks. I thought about the matter of communication in organizations, not only large things but also changes, strategy, goals. That is also a huge thing, a topic for a separate conversation, because there is much to do here and in general with transparency in firms. I often meet that there is no such transparency.
End of the conversation and recommendation
Rafał: Thank you very much for telling about the financial market in an accessible way, because I am convinced that after listening to this conversation it will be much easier to get into it not only for me but also for people who had not thought about it at all. If we wanted to expand our knowledge, I assume we will find you on LinkedIn and can write to you there. I will link your profile. Is there another place where you appear or write, or where you can be caught?
Adam: As for the IT sector itself, I am a professional partner and Ebury's main contact in the SODA Association, IT Corner. I am also a professional partner of the IT Ukraine Association. I am a recently proud member, thank you for accepting me into the circle of MBA graduates at the Polish Academy of Sciences. There too I hope soon to have an opportunity to realize myself, sharing knowledge. I invite you to my LinkedIn and write. Do not be afraid. I love sharing knowledge, in a very accessible way, using very simple language. Great thanks for the opportunity to share, Rafał, on your wonderful platform.
Rafał: Thanks, really the pleasure is mine, because I was seriously curious how it looks, and as I mentioned a few times, it looks easier than I thought, so a bomb. At the very end: I often ask my guests for a recommendation. It need not be on the subject of finance. If you have a book worth reading, a podcast, a blog or anything else where we could send our listeners to expand their knowledge, I invite you to share.
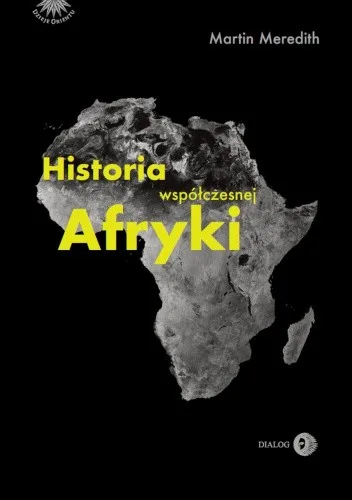
Adam: I read only history, and history of everything, so I usually read about 5 books at once. At the moment I am reading a fantastic history of Africa, from three thousand years ago to now. As for the financial area, I will not recommend one book, because that field is so developed already that it would be hard to recommend one author. Read history, because everything has already happened. It only repeats in a new edition, ever more nicely packaged. Maybe it speeds up a bit, but everything has already happened, as they say on the currency market: what goes up must go down.
Rafał: In the context of history I will pull your tongue. It is not my saying, but I liked it very much: it is not worth fully talking with people who do not know history about what will be, what was and what is now, because they are people who were as if born yesterday. I am a fan of history books, I am hooked to the max. You mentioned Africa, maybe you can give the title.
Adam: It is "Historia Afryki", the author is Meredith. Fantastically written, reads like a crime novel. We learn what happened on that great continent, where we were doing various other strange things here in Europe, and we come to the conclusion that until about 1500 it was more or less similar: all the time everybody was brawling with each other, bashing each other, trying to build some normal life. Later it of course diverged, Europe and Africa, but I recommend it, because it is a fantastic book. I like history books, but not boring ones, and this reads like a crime novel.
Rafał: Thank you for that recommendation. I will definitely add it, also to my list, which is long, but I cannot wait, because I always joke that after "Out of Africa" by Karen Blixen I am also hooked on that continent and often read about various countries to find out more. Once again thank you very much. It was a pleasure and I hope until next time.
Adam: Of course, we will be in touch. Regards to you all. Thanks and hedge your currency risk. Be conscious users of that fantastic phenomenon that is exchange rate volatility.
Rafał: Thanks, all the best.
Listen and watch
The same conversation in your favourite app.
The full edited transcript as a Markdown file, with the guest’s details and quotes.
Back to top